Language
en


Global payment connectivity is expanding rapidly, but moving money across borders is only the beginning. The real challenge lies in navigating each market’s regulations, payment ecosystem and risks, making local understanding essential to global trust.
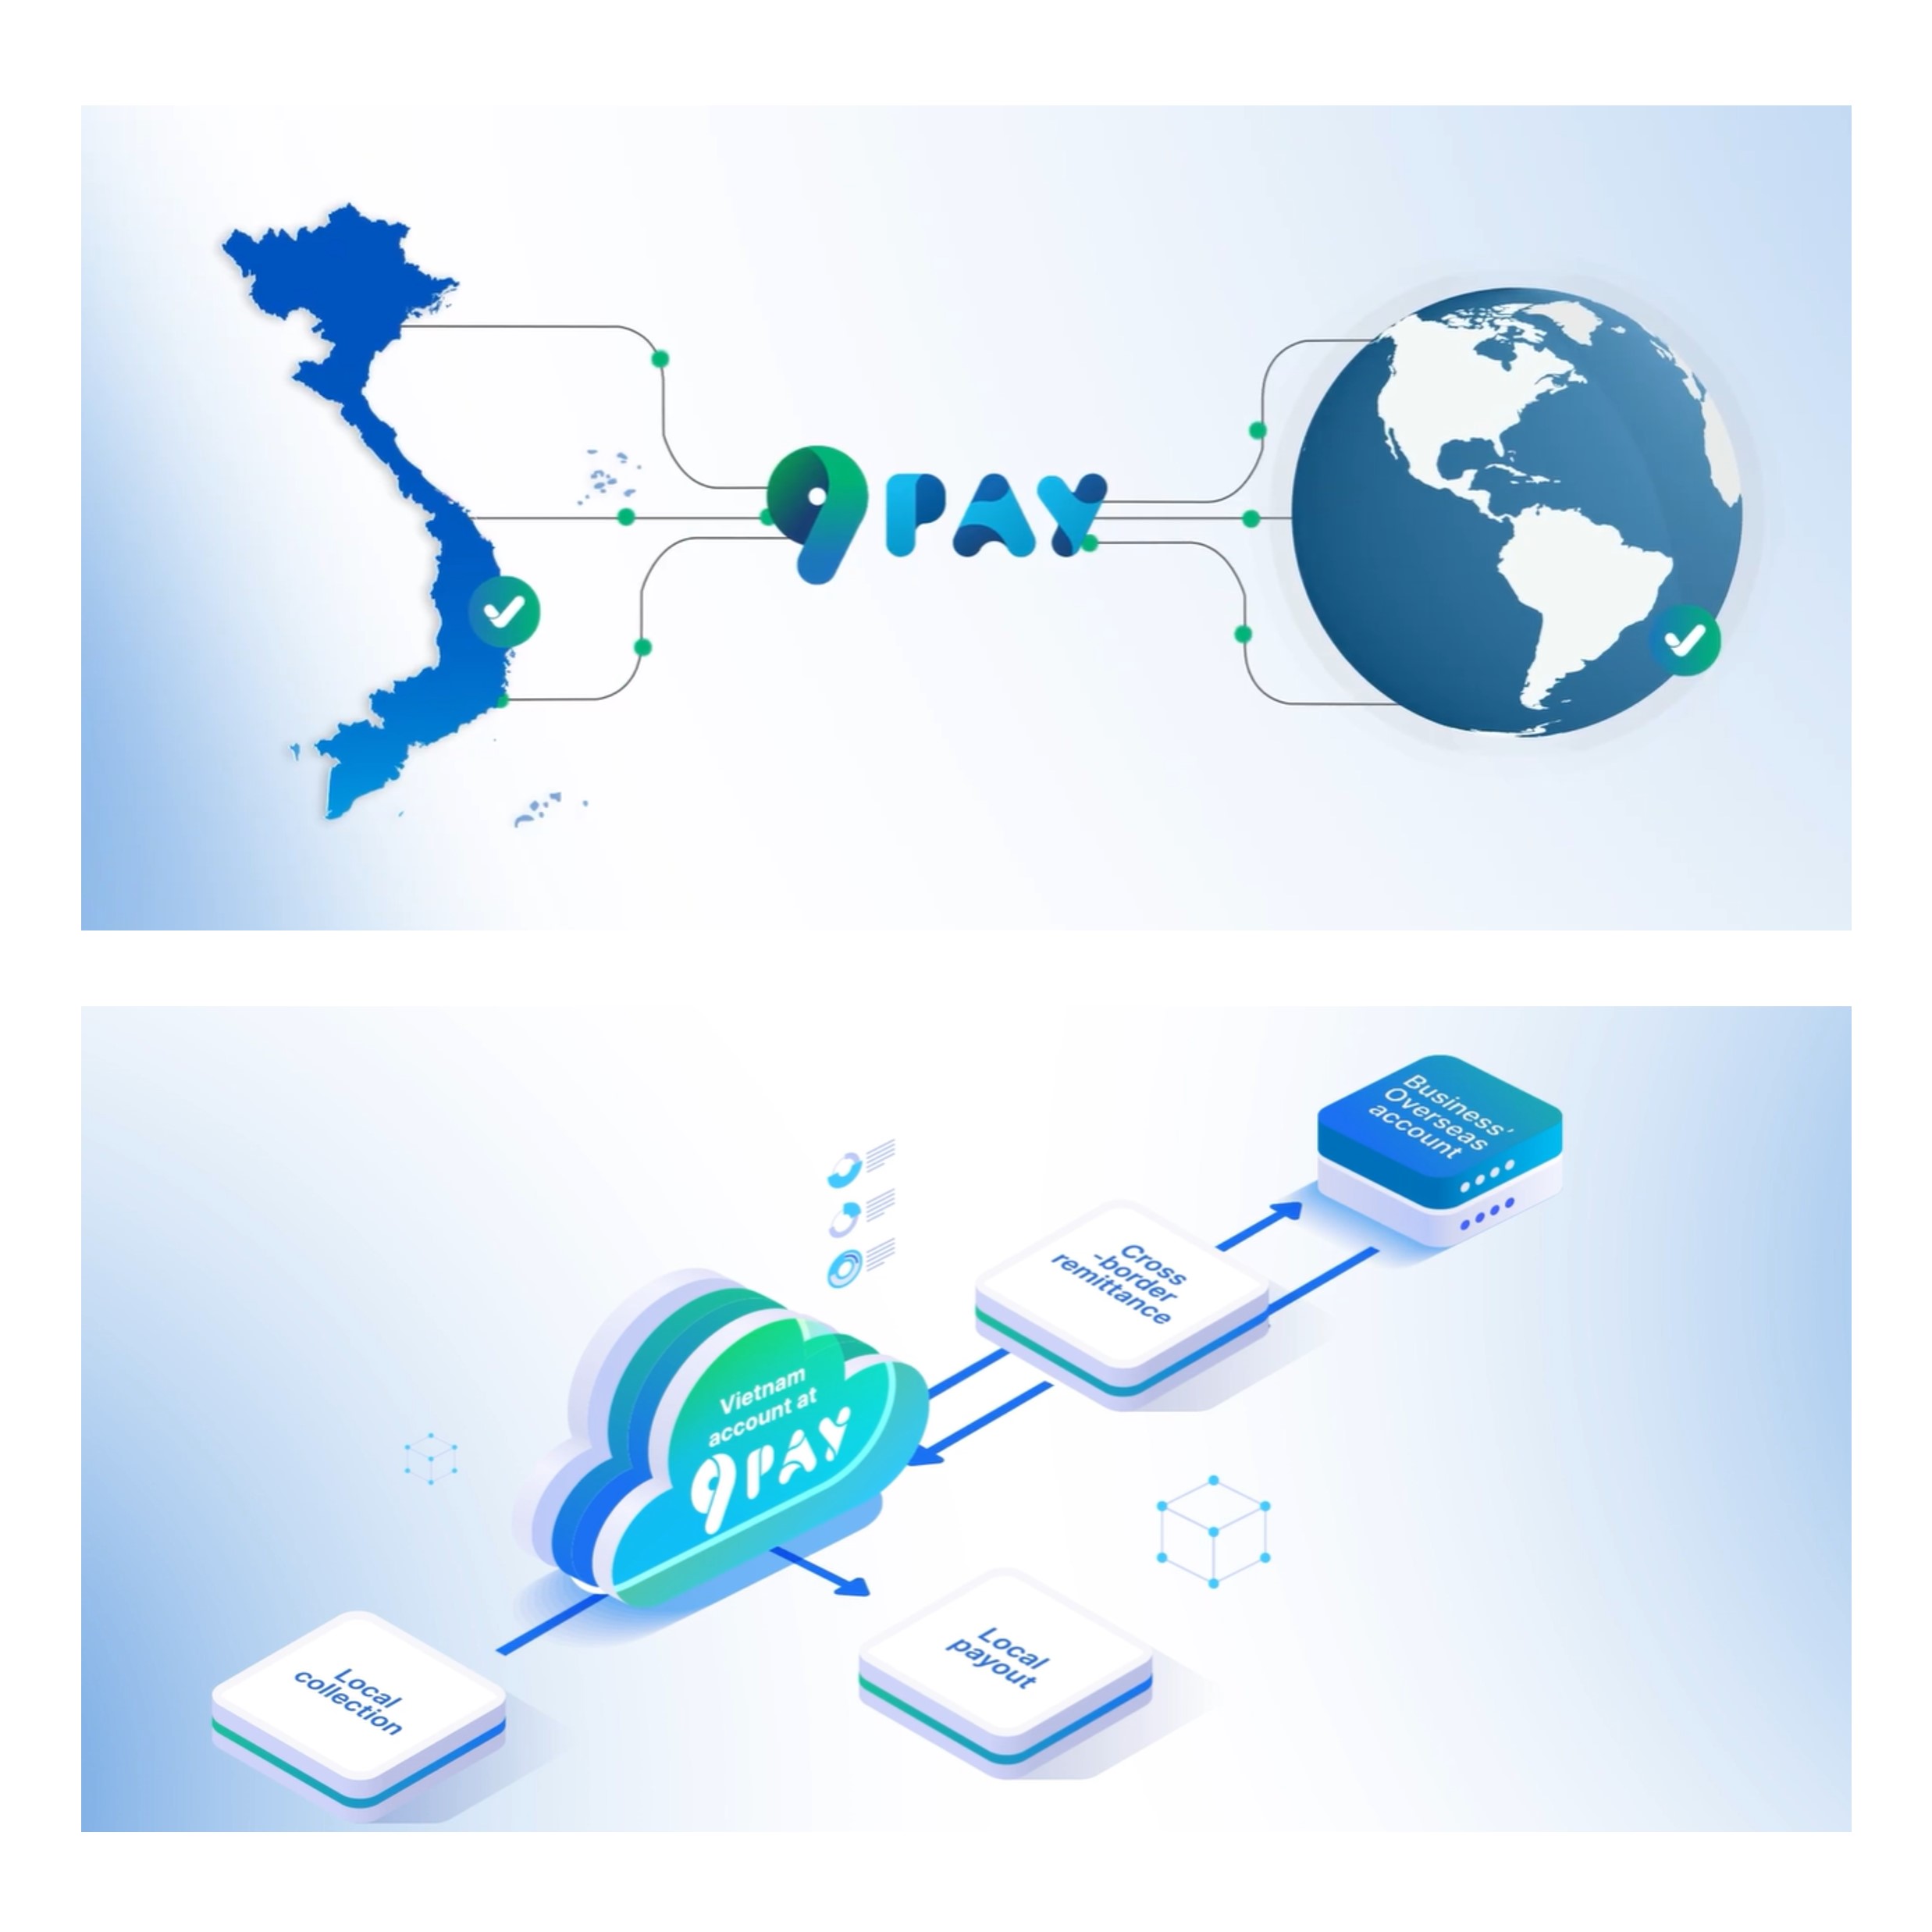
As cross-border commerce expands, payment infrastructure is being reshaped by technology, regulation and shifting capital flows. The global cross-border payments market is projected to reach US$238 billion, with Asia-Pacific among the fastest-growing regions, recording an annual growth rate of more than 9%.
For Vietnamese businesses expanding overseas and international brands entering Vietnam, cross-border payments involve far more than moving money between accounts. Each transaction operates within a complex framework covering anti-money laundering (AML), sanctions screening, source-of-funds verification, transaction monitoring and chargeback management.
The challenge is compounded by differences in payment ecosystems and regulatory frameworks. A model that works efficiently in one market cannot simply be replicated in another.
|
"Common bottlenecks include licensing, reliance on domestic payment infrastructure such as NAPAS, and settlement requirements in VND. Yet the biggest gap is often underestimated: market understanding and trust. Foreign businesses can struggle to build distribution networks without local relationships, while domestic fintechs benefit from their understanding of consumer behavior and the credibility built over time." - Ms. Nicole Nguyen, Founder at APAC DAO & Vietnam Fintech Summit |
 |
This makes local adaptation increasingly important. In Asian markets such as China and Japan, where business relationships often rely heavily on local networks and trust, even small gaps in regulatory compliance or risk management can disrupt payment flows. Cost efficiency alone is no longer enough; businesses also need partners that understand how each market works.
This is where the right local payment partner becomes a genuine business advantage - bridging a global payment model with the realities of the Vietnamese market, from regulatory navigation and ecosystem access to settlement and daily transaction operations.
 |
"Global connectivity is becoming increasingly accessible from a technology perspective. But for money to move reliably within a market, businesses need a strong understanding of the local payment ecosystem, regulations and transaction behavior" - Mr. Le Tuan Anh, Business Director at 9Pay |
For 9Pay, “local trust” is built through an established presence in Vietnam, including collaboration with regulators, connections with domestic banks and payment service providers, and established local payment infrastructure. These capabilities help integrate global payment technology and international money flows into Vietnam’s domestic ecosystem.
Technology itself is no longer a clear dividing line between Vietnamese and international fintechs. Domestic platforms are increasingly capable of meeting global requirements for security, service stability, processing speed and transaction success rates.
At 9Pay, this is supported by infrastructure compliant with PCI DSS Level 1 and ISO/IEC 27001:2022, a 24/7 operations team and continuous platform optimization based on operational data.
As global payment corridors evolve, the value of a fintech partner increasingly extends beyond moving money. Businesses need support in navigating local ecosystems and regulations, maintaining stable payment flows and managing operational risks.
This approach shapes 9Pay’s cross-border payment strategy.
“We do not view cross-border payments simply as moving money. It is about helping businesses enter new markets with confidence, understand how their money moves, manage risks and receive timely support,” Mr. Le Tuan Anh said.
From this perspective, “local trust” is more than an advantage for individual businesses. It reflects the growing capability of Vietnam’s fintech sector to meet global standards while providing the local connectivity and market understanding needed to support cross-border growth.
MAYBE YOU ARE INTERESTED
 Promotion news