Language
en


As transaction volumes grow, their operations expand in scale. Businesses may need not only to collect funds, but also to make payouts, process refunds, pay local partners, settle with merchants or move funds across borders.
Global companies often enter a new market with a specific need. A PSP may need to collect payments from local customers. A remittance company may need to pay recipients. An e-commerce platform may need a local payment gateway.
But few businesses stop there.
As transaction volumes grow, their operations expand in scale. Businesses may need not only to collect funds, but also to make payouts, process refunds, pay local partners, settle with merchants or move funds across borders. This is where the breadth of services offered by a local partner becomes important.
A remittance company may enter Vietnam with an inbound flow, paying remittances from Taiwan to recipients in Vietnam. As the business grows, it may also see demand in the outbound direction, from Vietnam to Taiwan. That creates a new need for collection services to support the additional flow.
If the local partner can provide both collection and payout, the company can expand its business model without adding a new partner for each requirement.
The same applies to a PSP. Its initial need may simply be domestic collection, allowing it to receive payments from local users. As transaction flows grow, the PSP may also need to transfer its revenue back to its home market. If the local partner also provides money transfer services, the PSP can manage both incoming and outgoing flows through the same partner.
In other words, the range of services offered by a local partner can shape a fintech’s ability to manage cross-border payment flows.These services are often complementary. Collection creates an incoming flow. Payout creates an outgoing flow. Money transfer moves funds between parties.
There is an important difference between a payment system that offers multiple services and one that simply has separate products.
If the services operate independently, the main benefit is straightforward: the fintech has a provider for each need. But when those services support related money flows, their value extends further.
A business may collect funds from one party and use part of those funds to pay another. A platform may receive money from customers and then pay merchants. A remittance company may need to collect funds in one direction while making payouts in the opposite direction.
This is where the discussion moves from payment processing to money-flow management. Operations can be streamlined, costs optimized and funds moved more efficiently.
When margins on individual transactions are under pressure, efficiency is not just about negotiating a few more basis points on fees. How funds are collected, paid out, settled and transferred also matters.
A fintech does not necessarily need to consolidate all of its transactions with one partner. In practice, working with multiple partners may still be necessary to diversify risk and maintain redundancy.
The value lies in having more choices: when a new need emerges, the business can build on services already available rather than establish an entirely new partnership each time.
For a global business growing rapidly, that flexibility has a real cost advantage. The time required to integrate, test, deploy and operationalize a new service all carry costs, even when they do not appear directly in the transaction fee.
According to McKinsey, cross-border payment value chains remain fragmented across multiple intermediaries and processes. The BIS has also identified interoperability between systems as one of the key challenges facing cross-border payments.
As businesses expand into new markets, they therefore need more than a local partner that can handle their current transactions. They need partners with a broad range of services that can support their needs as the business evolves.
—
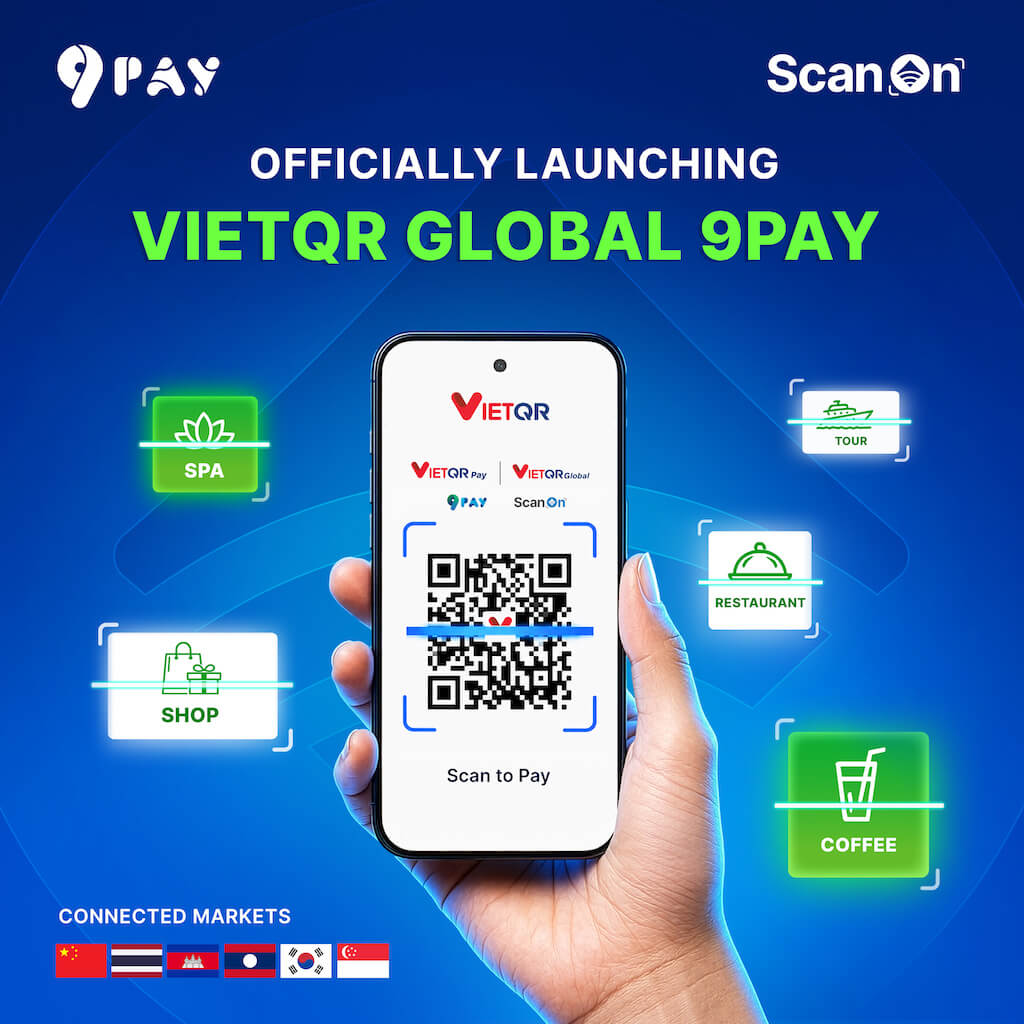
In Vietnam, 9Pay positions itself as a trusted local fintech partner with a broad range of payment services, from collection and payout to international money transfer.
9Pay is licensed by the State Bank of Vietnam as a payment intermediary and holds Direct Foreign Currency Receiving and Payment License, providing a regulatory foundation for its payment and cross-border transaction services.
As a member of the International Financial Center, 9Pay is also researching the use of blockchain technology in compliance with applicable regulations to enhance its existing B2B services.
With its broad range of services and regulatory foundation for cross-border payments, 9Pay aims to work alongside PSPs, remittance companies, global e-wallets and global merchants, supporting their expansion and growth in Vietnam.
MAYBE YOU ARE INTERESTED
 Promotion news